Bayesian Change-Point Detection and Fault Scoring in District Heating Systems
| Outlet | arXiv |
| Quartile |
My research develops econometric tools for data with persistence, trends and noise, and applies them to climate, energy and financial markets. Four themes run through it.
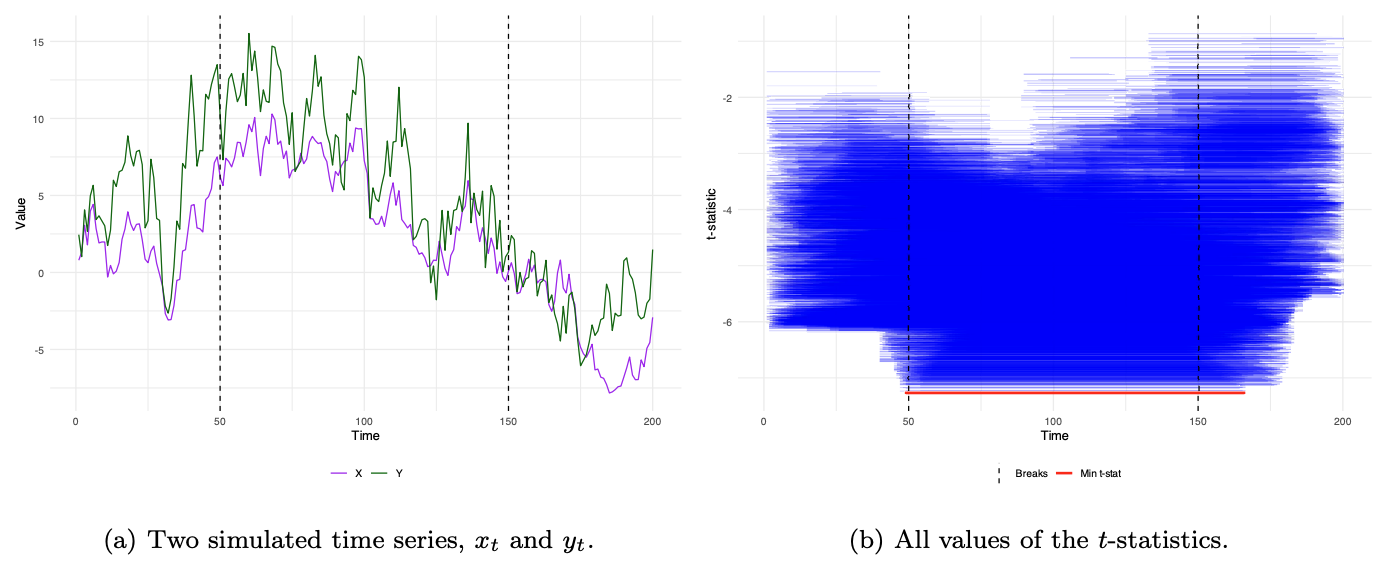
Long memory and persistence. Many economic and physical series forget shocks slowly. I study how long memory arises, how it survives aggregation, and what it means for forecasting and inference. This includes spurious regression under persistent processes. The work is available for practicioners in the Julia package LongMemory.jl.
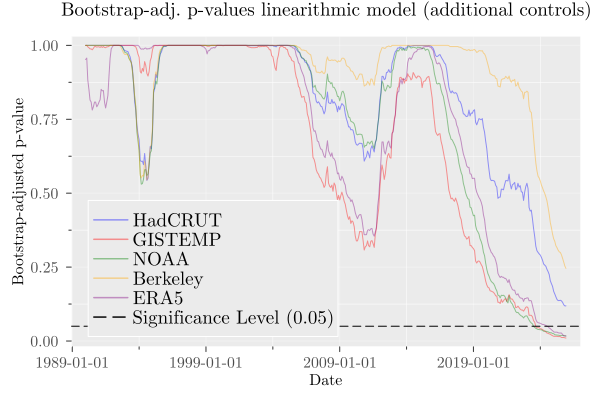
Climate econometrics. I use time series methods to ask how fast the climate is changing. Examples are detecting acceleration in global temperature, estimating the odds of breaching 1.5°C, and measuring the CO₂ airborne fraction under measurement error.
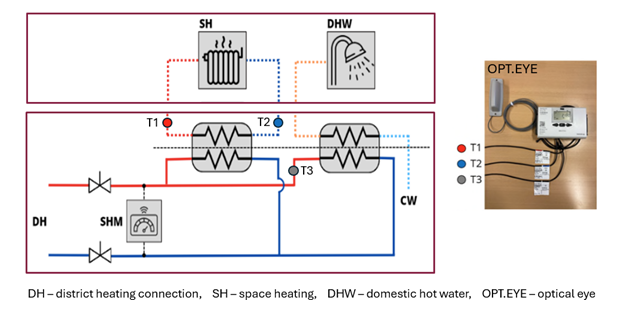
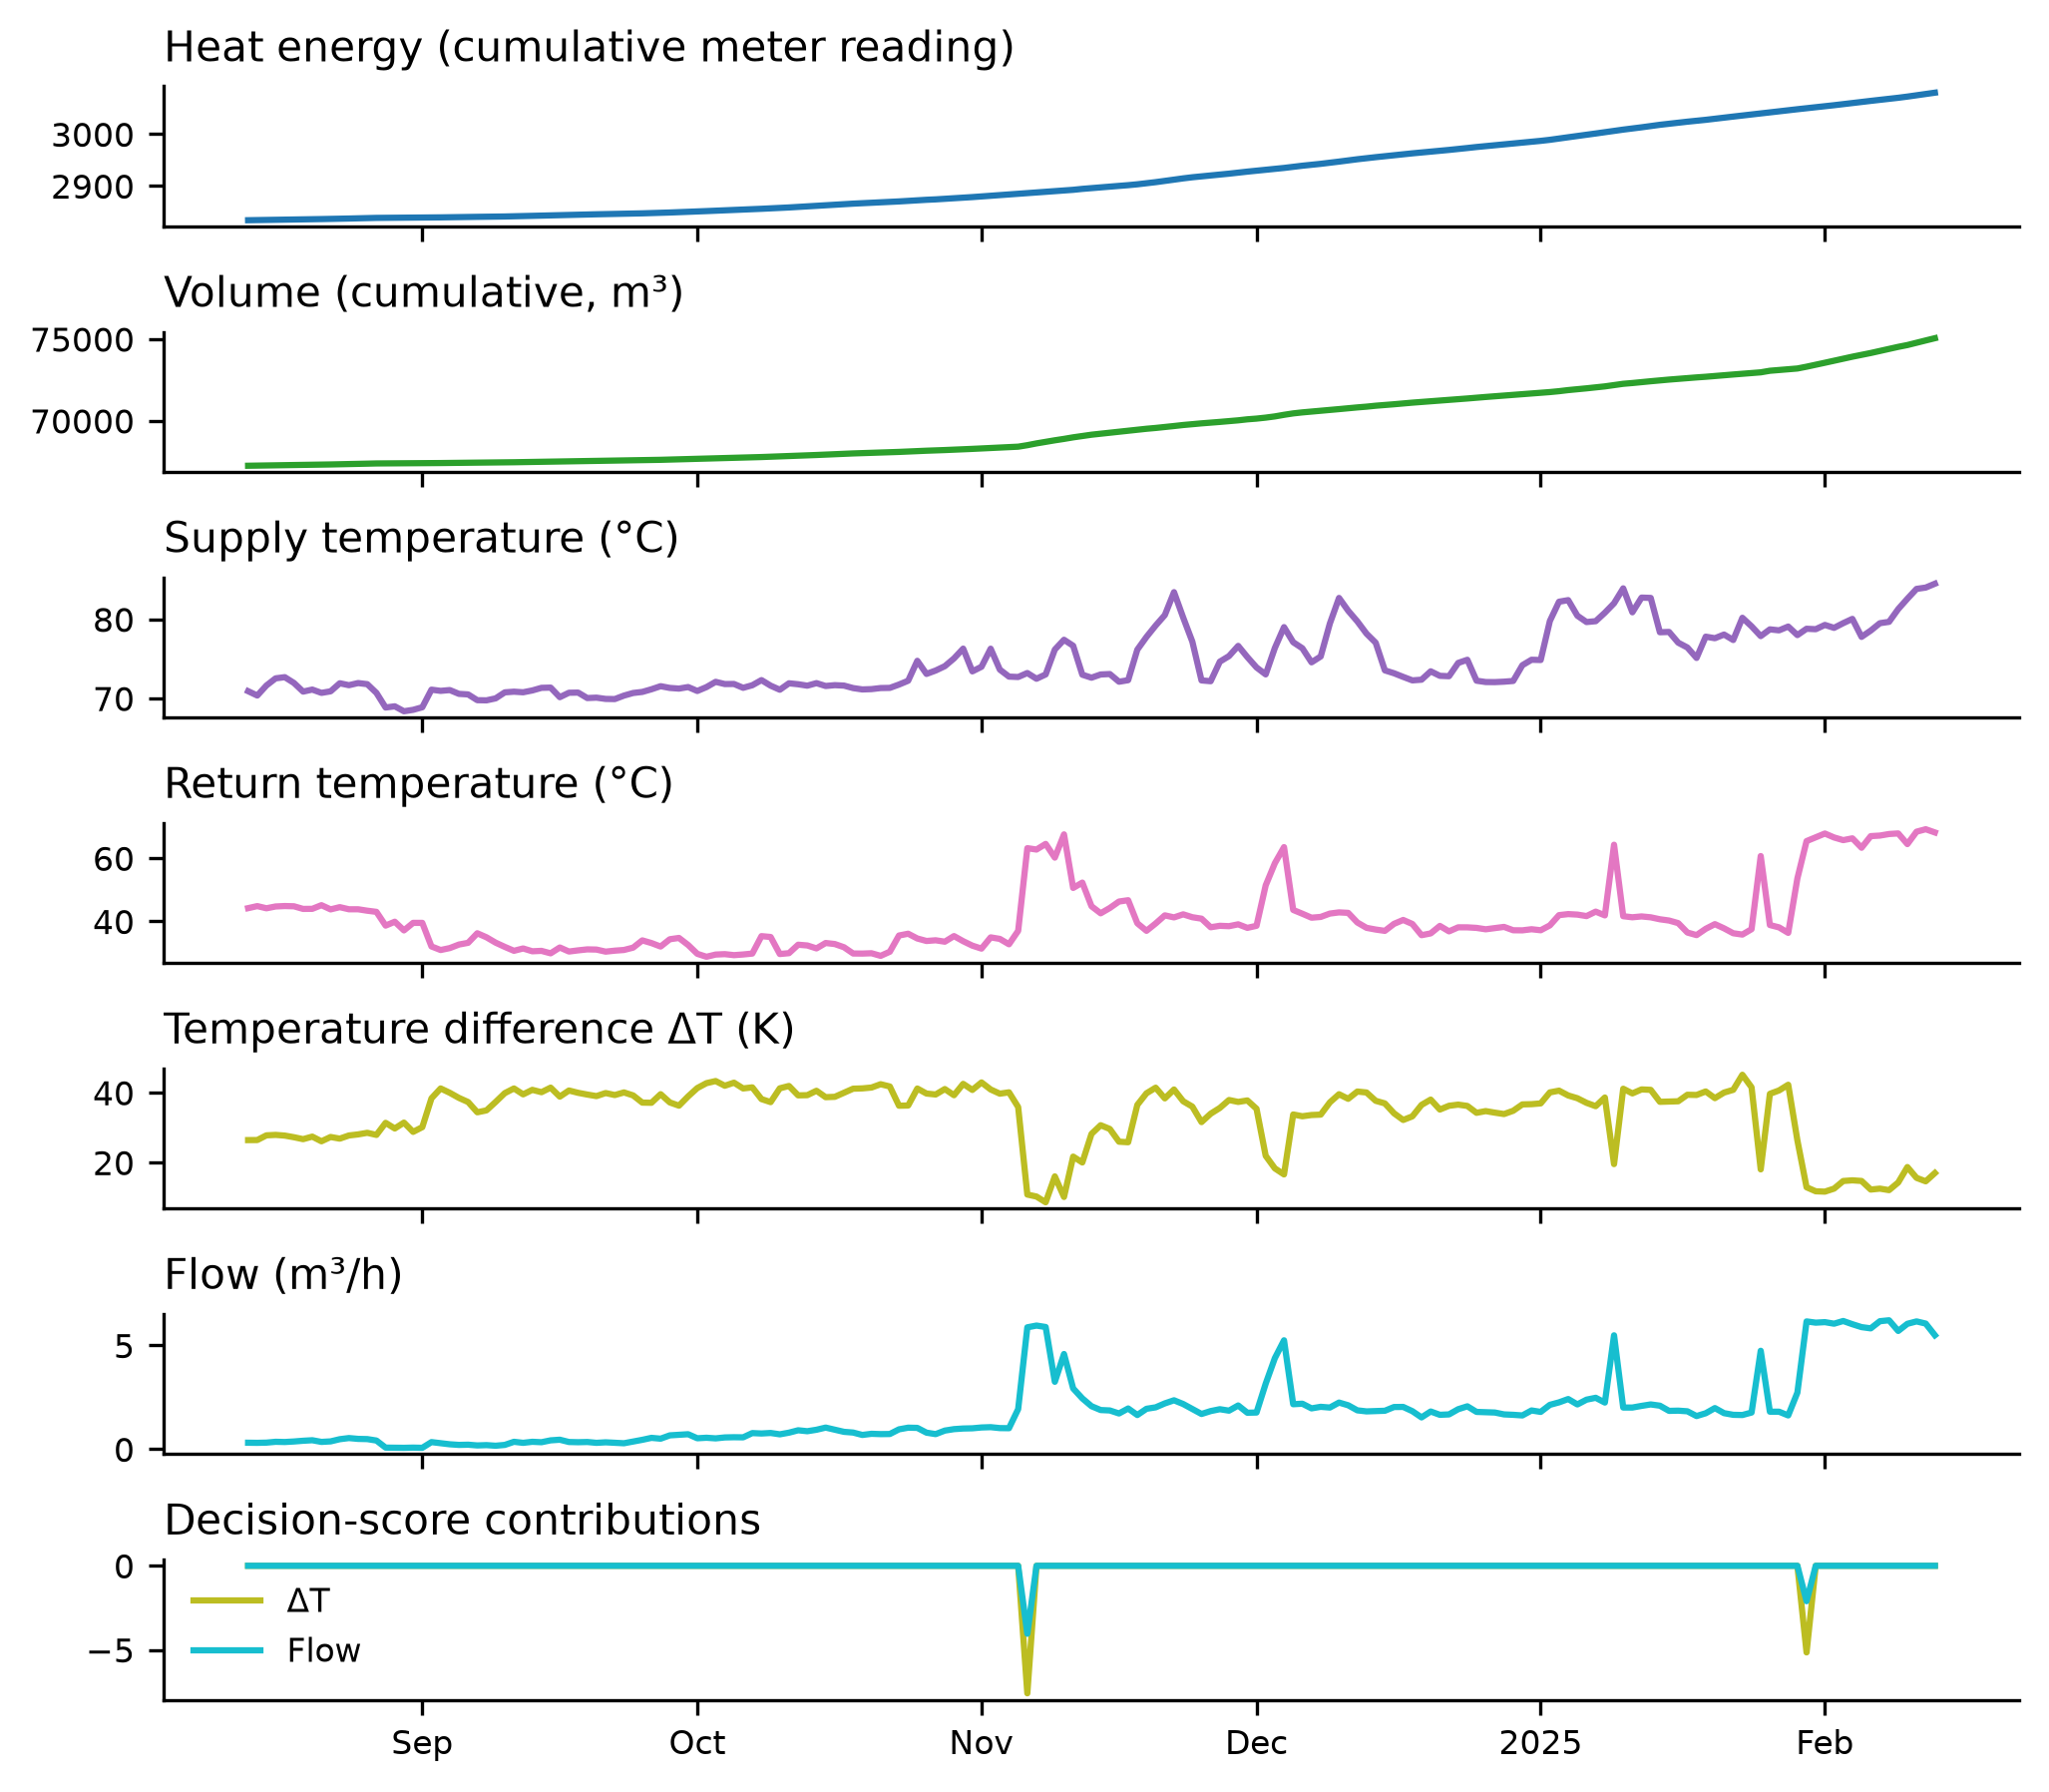
Energy and smart-meter data. Together with building-energy researchers, I analyse high-resolution heat and water meter data. The aim is to understand how households use energy, from clustering consumption patterns to separating space heating from hot water.
Financial markets and risk. I study volatility, risk and market reactions to shocks such as COVID-19, climate news and public controversies, often with high-frequency data.
Here you can find all my research. The articles are divided between published papers and working papers.
You can also follow my profiles on Scopus and Google Scholar.